

 22 October 2026
For decades, South Africans have treated property as the dependable foundation of an investment portfolio – the asset you could count on while shares lurched and the rand wobbled. After a stop-start few years for interest rates, and a surprise upward move in May, some investors are giving that reliable reputation a rethink.
Craig Mott, National Sales Manager for the Rawson Property Group, says it's a fair question to ask – it's just usually aimed at the wrong timeframe.
“Property has never been about what happens in a single quarter,” he says. “When people ask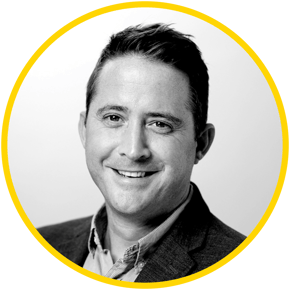 whether it's still safe, they're often reacting to a headline. The honest answer is that it depends on how long you plan to hold, and how well you buy in the first place.”
Safe compared to what?
Part of the difficulty is that “safe” means different things to different investors. For some it means no risk of loss; for others it means not lying awake when the market moves.
Property won't ever be the most liquid thing you own – you can't sell a house in an afternoon the way you can a share. But Mott argues that the same quality that frustrates people is also where the reassurance comes from.
“A property doesn't swing in value day to day the way equities can,” he says. “It's a tangible asset you can live in, rent out, or improve. And it's one of the very few investments where an ordinary buyer can put down a deposit and borrow the rest to own something that appreciates over time.”
That borrowing – known as gearing – is part of what has made property such an effective wealth-builder in South Africa. Used sensibly, it lets a modest deposit control a much larger asset. Used carelessly, it's also where the risk creeps in.
What the numbers say
The recent data tells a steadier story than headlines suggest. After several years in which house prices rose more slowly than inflation – meaning owners were technically going backwards in real terms – growth has turned positive again, both in nominal terms and once inflation is stripped out.
It isn't a boom. Nominal price growth is sitting in the low-to-mid single digits nationally. But for a long-term asset, that's arguably the healthier outcome.
“Slow and steady is what you want from something you're holding for ten or twenty years,” Mott says. “Runaway price growth usually means a correction is coming. Modest, sustainable gains are far easier to plan around.”
He's also careful not to flatten regional differences. The Western Cape has led the recovery, with tight stock keeping prices firm, but Mott points out that the upturn is now broadening.
“What's encouraging is that we're seeing momentum return to Gauteng and parts of KwaZulu-Natal, not just the Cape,” he notes. “A recovery that's spread across the country is more durable than one carried by a single province.”
Where the real risks sit
None of this makes property risk-free, and Mott is wary of anyone who suggests it is. The risks are real – they're just different from the ones most people worry about.
Affordability is the big one. May's rate increase was a reminder that borrowing costs don't only move in one direction, and a bond that's comfortable today can feel very different after a couple of upward surprises.
“The danger is rarely property itself – it's buying badly,” he says. “Overextending on the bond, choosing the wrong area, or banking on a quick resale. Those are the things that turn a safe asset into a stressful one.”
The other risk is liquidity. Property is a poor place to keep money you might need in a hurry, which is why Mott treats it as one part of a plan rather than the whole of it.
What makes the difference
Property's safety isn't automatic, but it's also not a matter of luck. It comes down to a handful of fundamentals that hold true regardless of where rates happen to be.
Location and quality still do most of the work – a well-chosen property in a sound area weathers downturns far better than a bargain in the wrong place.
Affordability headroom matters just as much: buying with room to absorb a rate increase, rather than stretching to the last rand, is what keeps an investment comfortable when conditions shift.
And then there's the temptation to wait for the perfect moment.
“Trying to time the market almost never works, and it costs people good opportunities while they wait,” Mott says. “If the fundamentals are right and you can afford it through a few rate cycles, the entry month matters far less than people think.”
The longer view
Asked whether property is still a safe investment, Mott's answer is neither a flat yes nor a hedge.
“Property is as safe as the decisions behind it,” he says. “Bought well, held patiently, and matched to what you can genuinely afford, it remains one of the most reliable ways to build wealth in this country. The safety isn't something the market hands you – it's something you build into the purchase.”
In a year of mixed signals, that's perhaps the most useful way to think about it. The question isn't really whether property is safe, but whether you're buying in a way that makes it so.
If you're weighing up whether property fits your plans, a good place to start is an honest conversation about your budget, your timeline, and the areas worth considering. A good agent can help you pressure-test the decision before you make it – no obligation, just a clearer picture. For more information contact 021 658 7100 or visit www.rawson.co.za


