

Introduction: Why Tenant Credit Checks Matter in South Africa
Placing the wrong tenant in a rental property can cost a property owner months of lost income and thousands in legal fees. Contested evictions in South Africa typically drag on for 3–6 months, and that timeline only starts once you file papers. The simplest way to avoid this is to screen potential tenants properly before anyone signs a lease agreement. Landlords check credit scores before renting properties for good reason - it is the single most reliable early-warning system available.
South African law governs the entire process. The National Credit Act (NCA), the Financial Intelligence Centre Act (FICA), and the Protection of Personal Information Act (POPIA) set the rules for how credit information, identity data, and personal details may be collected and used. Only a registered credit bureau may legally provide a credit report, and consent from the applicant is non-negotiable.
At Rawson Property Group, our rental agents run this screening process daily across our national franchise network. This guide walks you through exactly how to do it yourself - or shows you why partnering with a professional rental agency makes the entire process easier.
What you will learn:
- How to collect the right application details and obtain valid consent
- How to verify identity, income, and affordability before ordering a credit check
- How to order, read, and interpret a tenant credit report
- How to combine credit data with reference checks for informed decisions
- Which legal compliance issues to watch out for under NCA, FICA, and POPIA
Step 1: Get the Right Tenant Application and Written Consent
Before you request any data from a credit bureau, you need the tenant's explicit consent in writing. Landlords must obtain explicit written consent to request a tenant's credit report - this is a hard requirement under both the NCA and POPIA. South African credit bureau reports require the tenant's written consent under POPIA, and skipping this step exposes you to fines of up to R10 million.
Your tenant application form should capture:
- Full legal names and surname
- South African ID number or passport number
- Date of birth, marital status, and contact details
- Current and previous residential addresses
- Employer name, position, and employment duration
- Gross monthly income and existing financial obligations
- Names and contact details of at least one previous landlord and next of kin
- A clear consent clause authorising credit checks, background checks, and verification of rental history with previous landlords and employers
Keep all signed application and consent forms on record for at least five years. FICA requires estate agents - as Schedule 1 accountable institutions - to retain customer due-diligence records for audit purposes. This responsibility applies equally to private landlords managing their own rentals.
Step 2: Verify Identity and Basic Information
Identity verification is your first quick win before spending money on a credit check. Tenant screening includes ID verification and employment checks, and catching a fraudulent ID at this stage prevents costly mistakes later. A certified copy of the tenant's South African ID or passport is required for screening.
- Check the SA ID number format: 13 digits where the first six represent date of birth (YYMMDD), with a final checksum digit. A mismatch between the ID number and the applicant's stated date of birth is an immediate red flag.
- Compare the photo on the green barcoded ID or smart ID card against the person in front of you. Confirm that names match the application exactly.
- For higher assurance, verify the ID against the Department of Home Affairs population register. Service providers such as VerifyNow offer this, or work through a rental property agent like Rawson that already has access to compliant verification tools.
- Collect proof of residence - a recent municipal account or utility bill - to satisfy FICA requirements and confirm that the tenant's address history is consistent with their application.
- For foreign nationals, request a valid passport and work or residence permit, and verify the permit's validity period against the proposed lease terms.
Step 3: Confirm Income and Do an Affordability Assessment
A credit check alone is not enough. You need to confirm the tenant's ability to afford the rent over the full lease term. Rent should ideally be 25–30% of gross monthly income. For example, a property with monthly rent of R8,000 typically requires gross income of about R24,000.
Tenants should provide up to three months of payslips and bank statements for verification. Specifically, request:
- Last three months' payslips and an employment contract or confirmation letter for salaried tenants
- Three to six months' bank statements showing regular income deposits
- For self-employed tenants: management accounts, recent tax returns, and bank statements demonstrating consistent income
To run a simple affordability assessment, compare the proposed rent against net income after fixed expenses. PayProp's Rental Index (Q4 2025) found that tenants spend an average of 46% of income on debt obligations, with rent taking roughly 28.4%. This means looking at rent alone is not sufficient - total debt matters.
Professional estate agents and property managers document the affordability assessment as part of their managed lease process. This paper trail shows that landlords made informed decisions and acted responsibly, which is critical if disputes arise later.
Step 4: Order a Credit Check from a Registered Credit Bureau
Popular credit bureaus in South Africa include TPN, Experian, and TransUnion. Others such as XDS and Compuscan are also NCR-registered. A credit report from a registered bureau is recommended - never use unregistered or informal sources.
Here is how to order a tenant credit check step by step:
- Create an account with a credit bureau or use your rental agency's existing account. Rawson Property Group agents routinely access tenant checks via integrated property management systems.
- Capture the tenant's ID number and upload the signed consent form.
- Select the correct product - a "consumer credit profile" for general credit history, or a specialized Tenant Profile that shows rental payment behavior in credit checks. TPN's tenant profile reports, for instance, cost approximately R52.17 excl. VAT per search.
- Submit and receive the report. Tenant screening can take 3–5 business days for manual processes, though digital platforms often return results within hours.
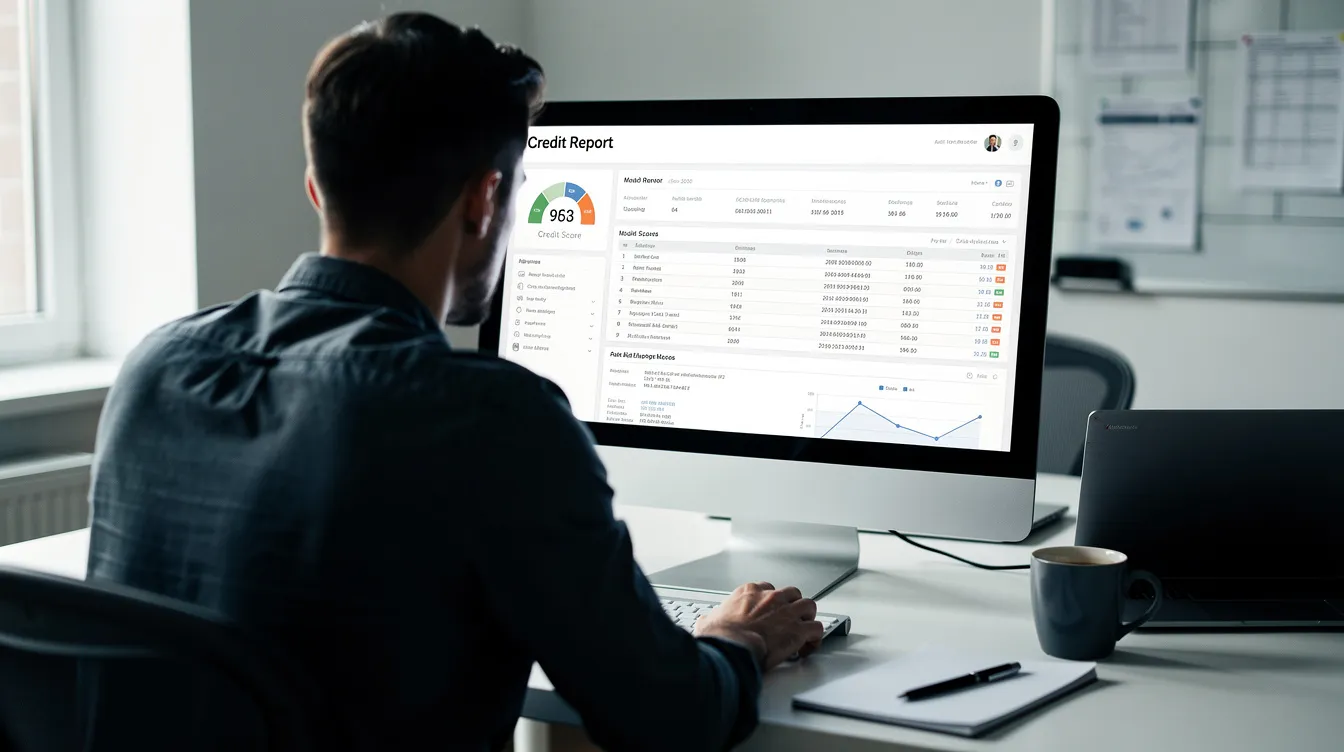
The report will show: credit scores, detailed credit history, open accounts and balances, arrears, judgments, defaults, debt review status, and previous addresses. A tenant credit check includes evaluating credit score, judgments, and rental history - all in one document.
Step 5: Read and Interpret the Tenant's Credit Report
Credit scores range from poor to exceptional, and each credit bureau uses a slightly different scale. A score below 600 is generally considered poor. Credit scores affect rental costs and loan eligibility, so understanding the number in context matters more than the number itself.
- Look at payment patterns: consistent on-time payments over several years are a strong positive signal, even if the overall score is moderate.
- Check for red flags: multiple recent defaults, court judgments, active debt review, or a pattern of late payments across several accounts.
- A low credit score does not automatically disqualify a reliable tenant. Older negative entries carry less weight than recent ones. Examine how much debt the tenant is carrying relative to income.
- Rental history should be included in credit reports for accuracy - if the bureau report does not show it, supplement with direct reference checks.
Use the credit report alongside the affordability assessment and references to make balanced, informed decisions rather than relying only on one number. Different bureaux may hold different data, so checking across more than one registered credit bureau can provide a fuller picture.
Step 6: Check Rental History and References
Conducting a tenant credit check involves verifying employment and landlord references - the credit report is only half the picture. A tenant's rental payment record is often as important as their general credit history, especially considering how costly late rent and property damage can be. About 80% of tenants benefit when rental histories are reported, because a clean record strengthens their application.
Collect references from:
- At least one previous landlord or managing agent
- The tenant's current employer (HR department or direct manager)
- Optionally, a personal reference with long-standing knowledge of the tenant
Ask previous landlords these specific questions:
- What was the monthly rent, and were payments made on time?
- Did the tenant take reasonable care of the property?
- Were there complaints from other tenants or neighbours?
- Was the deposit refunded in full, or were deductions made for damages?
- Would you rent to this tenant again?
Some credit bureaus and services like the tenant profile network record lease payment data directly. Using estate agents with structured lease management systems - such as those in the Rawson network - helps ensure rental history is captured accurately for future lease renewals and negotiations.
Step 7: Combine All Information and Decide Fairly
At this point, you should have a credit report, an affordability assessment, identity verification, income proof, and reference checks. Combine everything into a single risk view before making your decision.
- Set written criteria in advance - for example, a minimum credit score band, maximum debt-to-income ratio, and rent capped at 30% of gross income. Apply these consistently to every applicant. Tenant selection must not discriminate based on race, gender, or other prohibited grounds under the rental housing act.
- If declining an application based on credit information, inform the applicant and refer them to the relevant credit bureau to dispute errors. Transparency here protects you legally.
- In borderline cases, negotiate risk-mitigating measures: a higher deposit (held in an interest bearing account as required by law), a co-signer or guarantor, or a shorter initial lease term. This approach helps you reduce risk without rejecting the right tenant outright.
- Document the entire process and your reasoning. This creates actionable insights for future property investment decisions and protects against compliance issues.
Legal and Compliance Considerations (NCA, FICA, POPIA)
Three laws shape every step of tenant screening in South Africa. Understanding them is not optional - non compliance carries real consequences.
- The NCA regulates how credit checks and credit bureau information may be used. Only NCR-registered credit bureaux may collect and disseminate consumer credit information, and tenants have the right to inspect their credit file once per year for free.
- FICA requires estate agents to perform customer due diligence, verify identity, and retain records for at least five years. Confidentiality laws require secure handling of personal applicant data during tenant checks.
- POPIA mandates that you collect only necessary data, obtain explicit consent, protect personal information, and use it solely for the stated purpose - in this case, tenant vetting and lease management. Ensuring compliance protects both landlords and tenants.
- IFRS 16 requires lessees to record most leases on balance sheets, and effective lease management reduces audit fees by nearly 30%. Lease management helps maintain compliance with accounting standards and financial reporting requirements - particularly relevant for landlords with larger portfolios.
Working with a reputable agency like Rawson ensures that lease agreements and screening processes align with current regulations and accounting standards.
How Rawson Property Group Can Help Landlords with Tenant Screening
Managing key processes like identity verification, affordability assessments, credit checks, and reference checks across multiple properties takes significant time. The global lease management market was valued at USD 4.4 billion in 2020, and for good reason - effective lease management can cut 30–40% of repetitive task time, helping property managers streamline operations and control costs through one platform with a user friendly interface.
Rawson Property Group handles the full screening process for residential and commercial landlords:
- Access to registered credit bureaus and integrated compliance management tools that deliver smooth operations across lease documents, rent collection, contracts, and maintenance
- Professionally drafted lease agreements and ongoing support throughout the lease term, from handling late payments to managing eviction procedures when prevention fails
- A fee structure that delivers real benefits: reduced risk of non-payment, legally compliant documentation, and peace of mind that your money and property are protected
Finding the right tenant is the single most important step in any property investment. Contact your nearest Rawson franchise or enquire online to let our rental agents handle tenant screening, lease management software integration, and day-to-day property management - so you can focus on growing your portfolio.


